A useful fact to keep in mind
DAN states that its dive accident plans can pay 100% of eligible accident medical expenses up to US$500,000, subject to plan terms.
Check the sourceDo I need scuba diving insurance in Hong Kong?
When a dedicated policy may be worth considering
There is no single answer for every diver. A short introductory session, a local boat day and a multi-day dive holiday create different exposures, while your Hong Kong medical, travel or employer insurance may already have specific water-sports wording. The useful question is not simply whether a policy has the word ‘diving’ in it, but whether it responds to the exact activity, depth, certification and location you plan to undertake.
A dedicated dive accident policy is worth investigating when your ordinary health or travel cover excludes pressure-related injury, hyperbaric treatment, emergency transport or training. It can also be sensible if you are travelling with expensive equipment, diving repeatedly, joining a course, or visiting a destination where treatment and evacuation could be costly. Conversely, buying a second policy without checking coordination, territory and exclusions may leave you paying for overlapping protection rather than improving it.
Start with the provider’s written terms and your own policy schedule. Ask whether recreational diving and supervised training are both covered, whether a recognised certification is required, and whether the policy applies to Hong Kong waters, a liveaboard or a trip that begins locally. Keep the certificate, emergency number and claims instructions offline; a phone signal on a boat is not something to assume. For a structured comparison, see dive accident insurance versus travel insurance.
- Consider dedicated cover if your existing policy excludes diving, hyperbaric treatment or emergency evacuation.
- Check whether the policy covers training, not only certified buddy dives.
- Save policy documents and emergency contacts before leaving shore.
Does travel insurance cover scuba diving in Hong Kong?
Read the activity, depth and medical-assistance wording
Travel insurance sometimes includes scuba diving, but ‘water sports included’ is not enough evidence. The activity may be limited to a stated maximum depth, a particular certification level, or a supervised excursion with a licensed operator. Some plans cover an introductory experience but exclude independent dives; others distinguish between recreational diving, technical diving, freediving and competition. Read the definition and exclusions rather than relying on a sales headline.
Check five connected points. First, confirm the maximum depth and whether it is measured by the planned profile or the policy’s definition. Second, check certification and supervision rules, including what happens if a diver is learning. Third, ask whether medical treatment, a hyperbaric chamber and emergency transport are separate benefits or exclusions. Fourth, confirm equipment loss, trip cancellation and personal liability limits. Fifth, check geographic scope, activity dates and whether a pre-existing medical condition changes eligibility.
DAN’s official dive accident information lists hyperbaric chamber treatment, physician and hospital charges, and emergency transportation among possible benefits, but it also stresses that coverage varies by plan and that the issued policy controls. That is a useful illustration of why a benefit list is not a promise that every claim qualifies. For evacuation-specific questions, read dive accident insurance emergency evacuation coverage and ask your insurer to confirm the exact wording in writing.
When a sales agent says ‘covered’, ask for a sample scenario: a supervised beginner dive, a certified shore dive, a boat trip cancelled by illness, and a suspected decompression illness requiring transfer. The answer should state what is covered, the limit, the excess, who arranges transport and what documents you must produce. If you cannot get a clear answer, treat the activity as uninsured until clarified.
- Do not infer cover from a generic ‘adventure sports’ label.
- Match the policy’s depth, certification and supervision rules to your actual plan.
- Request written confirmation of emergency transport and hyperbaric treatment.
What does scuba accident insurance cover?
Compare exclusions, emergency support and claim limits
Scuba accident insurance is generally designed around an injury caused by a covered dive, rather than the whole cost of a holiday. Depending on the plan, it may address eligible medical treatment, hospital or physician charges, hyperbaric care, emergency transport and sometimes search-and-rescue. Some policies add accidental death, disability, delayed return travel or unintentionally damaged diving equipment. Those headings are starting points for comparison, not a substitute for the certificate and exclusions.
The exclusions deserve equal attention. Look for limits involving unqualified or unsupervised diving, depth beyond the stated limit, intoxication, deliberate rule-breaking, medical conditions, war or civil disturbance, and equipment used for commercial work. Ask whether the incident must be reported immediately, whether the insurer must authorise evacuation, and whether you can choose a hospital. A policy can be generous on paper yet difficult to use if its assistance procedure is not practical from a moving boat.
DAN states that its dive accident plans can pay 100% of eligible accident medical expenses up to US$500,000, subject to plan terms. This is a concrete example of a limit and eligibility condition, not a recommendation or a Hong Kong price. It shows why you should compare both the headline maximum and the definition of ‘eligible’. Also check whether cover is primary or secondary, and whether another insurer must be billed first.
For decompression-related concerns, does scuba insurance cover decompression sickness is a useful question to take to an insurer, but do not use an article as medical diagnosis. A diver with worrying symptoms should follow the operator’s emergency plan and seek urgent professional care. Insurance planning supports safety; it never replaces a trained dive team, conservative decisions or local emergency services.
- Compare treatment, evacuation, search-and-rescue, repatriation and equipment benefits separately.
- Check the excess, aggregate limit, authorisation process and claims deadline.
- Keep incident records, operator details and receipts if a claim is needed.
A practical pre-dive insurance check
Turn policy language into a decision you can use
Before booking, write down your planned activity in plain language: introductory or certified dive, shore or boat entry, expected maximum depth, number of dives, equipment ownership and whether an instructor or divemaster will be present. Give that description to the insurer rather than asking the vague question ‘am I covered?’. Save the reply with the policy number and the name of the representative who answered.
Then test the assistance route. Who calls the chamber or ambulance? Is prior authorisation required except in a life-threatening emergency? Does the insurer pay the provider directly or reimburse you? Is a Hong Kong hospital network available, and is marine transfer treated differently from road or air transport? These operational details matter more than a colourful brochure when weather, distance and language make a claim stressful.
Finally, align the cover with your own readiness. If you have a new diagnosis, medication change, recent procedure or concern about fitness to dive, seek advice from an appropriately qualified clinician and tell the insurer what it asks you to disclose. Do not conceal health information to obtain a lower premium. Insurance does not make a medically unsuitable dive suitable, and a policy exclusion can affect a claim even when the incident feels accidental.
Compare the cover you are actually buying
A simple worksheet for Hong Kong dive plans
Use the table as a conversation guide, not as a ranking of insurers. ‘Existing travel policy’ may be adequate for a straightforward trip only after its diving clause is confirmed. A dedicated policy can fill a medical-accident gap, while a combined arrangement may make sense when cancellation, baggage and medical evacuation all matter. In every case, the certificate and exclusions take priority over an informal summary.
Remember that the cheapest option is not automatically the most useful. A low limit, high excess or narrow definition of recreational diving may be poor value if the planned activity falls outside it. Conversely, broad cover may include benefits you do not need. Compare the scenario, response process and limits first, then compare premiums.
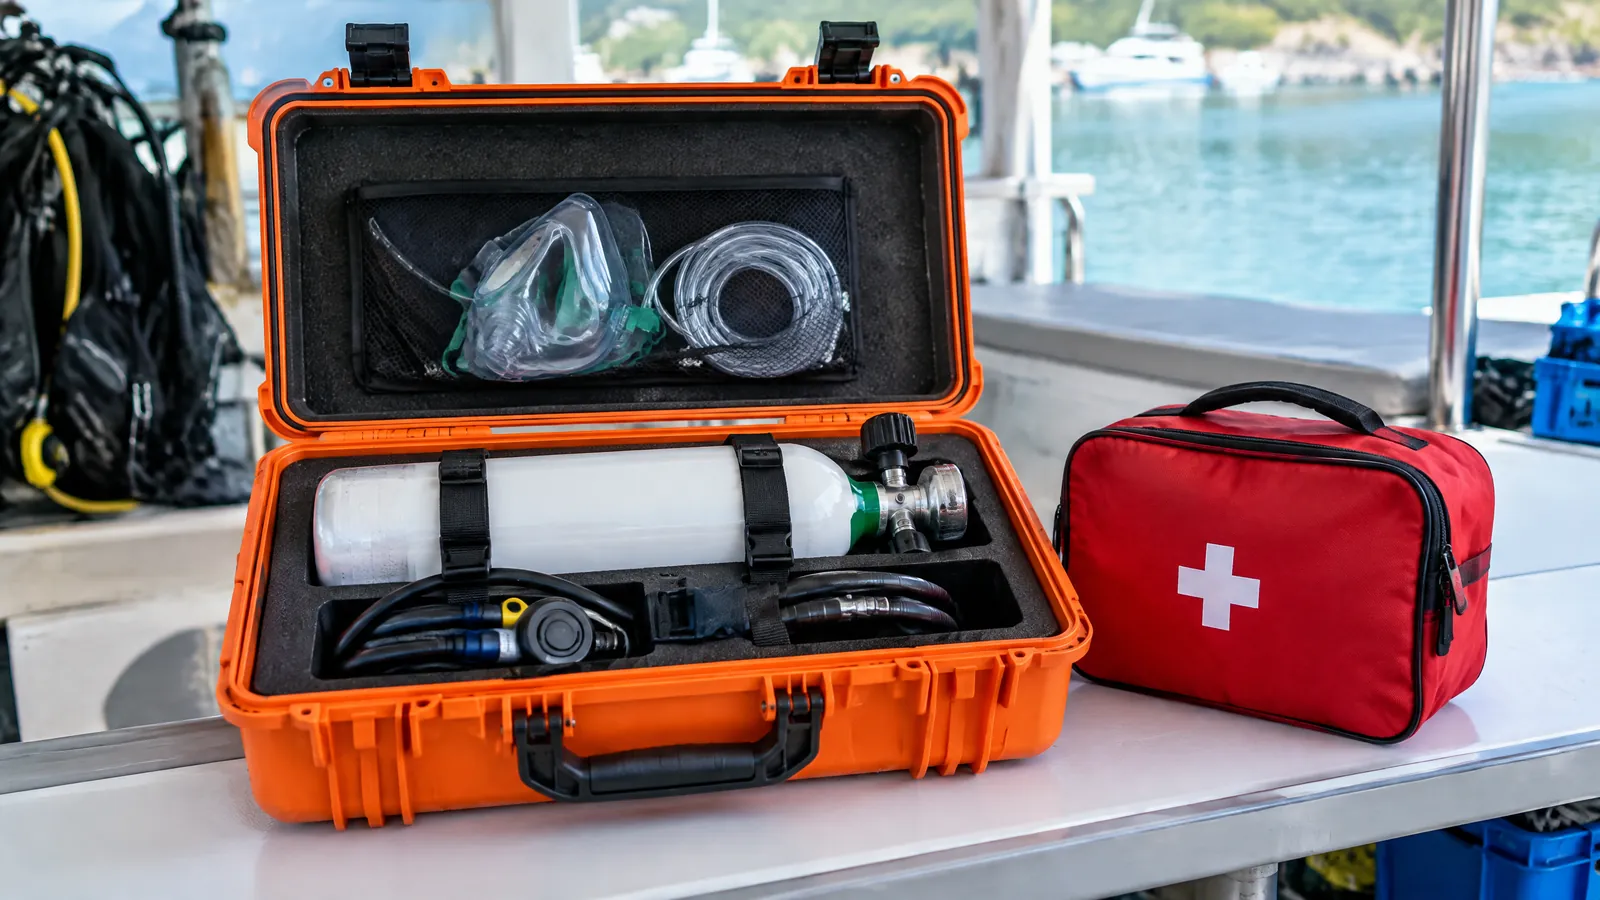
Hong Kong booking and health boundaries
Ask the right people before you commit
An operator can explain the planned activity, supervision, equipment and emergency arrangements; an insurer must explain the contract; and a clinician must address individual fitness questions. Keep those roles separate. DiveHarbour can help you frame practical questions before a course or activity, but cannot interpret or sell an insurance policy. If you are considering pregnancy or a major health change, read can you scuba dive while pregnant in Hong Kong and obtain individual clinical advice rather than relying on a general web answer.
A routine medical check-up is not an automatic insurance requirement, and there is no universal interval that applies to every diver. The appropriate timing depends on health, age, symptoms, certification requirements and clinical advice. For planning questions, how often should divers have a medical check-up in Hong Kong can help you prepare, but it cannot replace a clinician’s assessment or an insurer’s disclosure rules.
Before payment, ask for the final price, cancellation terms and what is included in the activity booking separately from insurance. Fees are non-refundable unless the written terms say otherwise; make-up sessions are available only where written terms permit, with no guaranteed reschedule date. If weather, illness or operator changes affect a booking, contact the provider promptly and keep the written response.
Which protection question should you ask first?
| Option | Best for | Check |
|---|---|---|
| Existing travel insurance | A trip where diving is an incidental activity | Diving definition, depth, certification, medical and evacuation limits |
| Dedicated dive accident insurance | Frequent divers, courses or policies with diving exclusions | Eligible injury, hyperbaric care, transport, excess and authorisation |
| Combined travel and dive cover | Divers needing both trip disruption and dive-medical protection | Primary/secondary status, overlapping exclusions and total limits |
| No confirmed cover yet | Anyone whose insurer gives an unclear verbal answer | Pause booking or obtain written confirmation before entering the water |
Scuba Diving Insurance in Hong Kong: What to Check — common questions
Is scuba diving insurance legally required in Hong Kong?Toggle answer
There is no blanket requirement stated here for every recreational diver. Requirements and sensible protection can differ by operator, course, destination and policy. Check the activity provider's terms and your insurer's wording before relying on existing cover.
What should I ask an insurer before diving?Toggle answer
Ask whether recreational and training dives are included, and confirm depth, certification, medical-assistance, emergency-transport, equipment and exclusion terms. Request the answer in writing and keep the policy details accessible during your Hong Kong trip.
Does travel insurance automatically cover decompression sickness?Toggle answer
No. Some policies may cover eligible diving injuries, while others exclude pressure-related conditions or impose depth, certification or supervision limits. Ask specifically about decompression illness, hyperbaric treatment and transport, and follow the issued policy rather than assuming a general sports benefit applies.
Are insurance or dive-activity fees refundable?Toggle answer
Fees are non-refundable unless the written terms say otherwise. Make-up sessions are available only where written terms permit, and no reschedule date is guaranteed. Ask the provider about cancellation, weather and illness procedures before paying.
Take the question with you
The safest next step is to describe your exact Hong Kong dive plan, send it to your insurer and request a written answer covering training, depth, treatment and evacuation. Save that answer with your policy documents, then confirm the operator’s emergency process and your own health readiness. Clear wording is more valuable than an assumption that ‘travel insurance’ or ‘diving insurance’ covers every scenario.
Sources worth checking
- DAN Dive Accident Insurance
DAN says its plans can cover hyperbaric chamber treatment, physician and hospital charges, and emergency transportation; it also states that eligible accident medical expenses may be paid up to US$500,000, subject to plan terms and exclusions.
Useful next reads for your plan
If you are still comparing routes, these related pages give you practical questions to bring into your next conversation with an instructor.
Put your plan into practice
Useful planning guides
Dive Insurance Claim Checklist for Hong Kong Divers
Use this dive insurance claim checklist worksheet to compare practical options, check key decision points, and confirm current details with DiveHarbour.
dive insurance claim checklist